Linking Range Advantage Recognition to Timing Sector Rotations in Cyclical Commodity Futures Contracts for Mid Career Traders
Paul Bauer · Sep 17, 2026
Linking Range Advantage Recognition to Timing Sector Rotations in Cyclical Commodity Futures Contracts for Mid Career Traders
Range advantage recognition, a concept drawn from structured decision frameworks in competitive card play, connects directly to the process of identifying timing edges when shifting allocations across cyclical commodity futures such as crude oil, copper, and agricultural contracts; mid-career traders often map these parallels by treating range construction as a method for narrowing entry and exit points during supply-demand shifts that occur in energy, metals, and grain markets.
Understanding Range Construction in Decision Frameworks
Traders apply range construction by defining intervals where price action is expected to hold certain probabilistic edges, and this approach mirrors the way sector rotation decisions rely on identifying periods when one commodity group outperforms another due to macroeconomic cycles; data from the Commodity Futures Trading Commission shows open interest fluctuations in energy contracts frequently precede rotation signals into metals by four to six weeks during inventory drawdown phases.
Those who study futures positioning note that recognizing when a contract sits inside or outside its typical range allows for clearer identification of rotation triggers, such as when copper futures break above multi-month averages while natural gas remains range-bound, prompting allocation adjustments without requiring full market exits.
Applying Range Advantage to Cyclical Commodity Timing
Cyclical commodity futures exhibit repeating patterns tied to inventory reports, weather events, and industrial demand, and mid-career professionals link range advantage recognition to these patterns by monitoring contract spreads that widen or tighten ahead of rotation points; for instance, when soybean futures enter a narrow range during harvest while crude oil expands its daily range on geopolitical news, historical positioning data indicates capital often flows toward energy exposure within subsequent sessions.
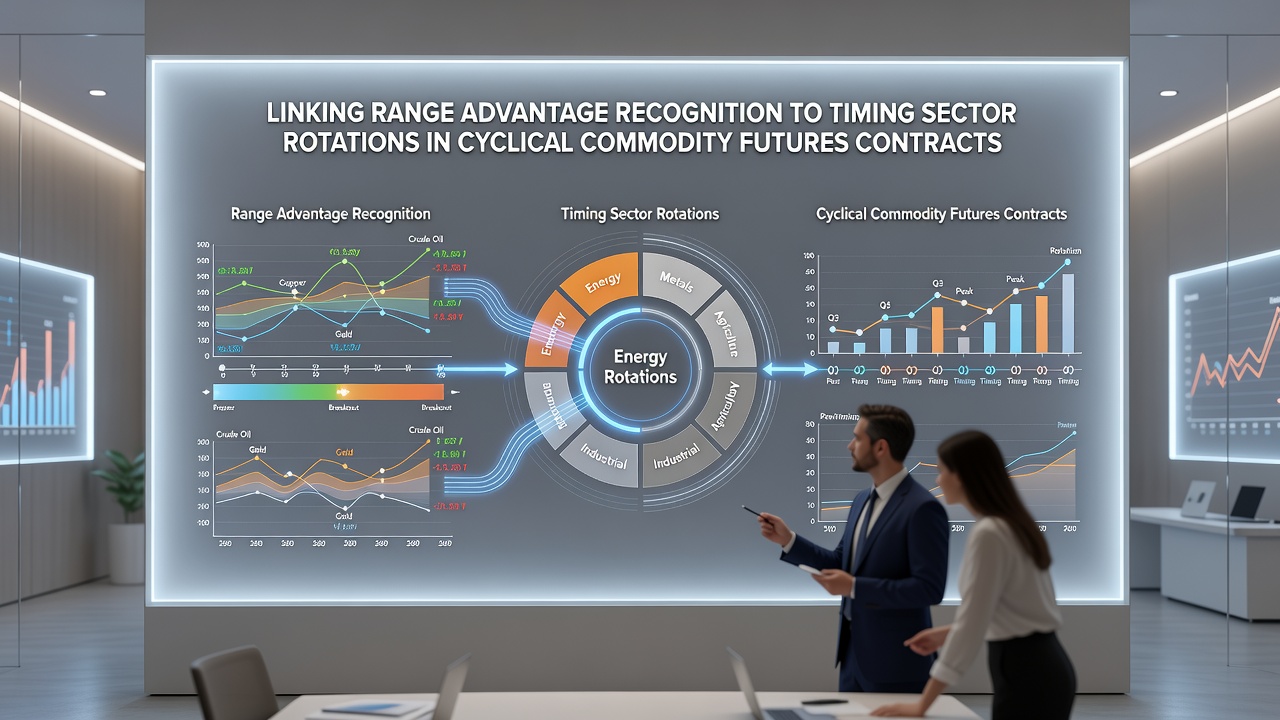
Research published by the Bank of Canada on commodity price cycles highlights that rotation opportunities between energy and base metals occur most reliably when volatility metrics cross established thresholds, a condition that aligns with range advantage calculations used to filter low-edge setups from higher-probability transitions; observers tracking September 2026 inventory releases note similar spread behavior emerging in live cattle and gold contracts amid shifting global demand indicators.
Practical Mapping for Mid-Career Portfolio Adjustments
Mid-career traders integrate these concepts by maintaining separate range matrices for each commodity class, updating them weekly with settlement data and open interest figures so that rotation decisions rest on quantifiable boundaries rather than discretionary calls; when a futures contract moves outside its defined range while correlated sectors remain inside theirs, allocation shifts toward the expanding range often follow documented seasonal tendencies reported in industry studies from the Australian Bureau of Agricultural and Resource Economics.
Position sizing within these rotations draws on the same logic that governs range betting intervals, where exposure scales according to the distance from range edges and the speed of boundary breaks; contract roll periods add another layer, as traders who track range violations near expiration dates frequently adjust exposure earlier than those relying solely on fundamental forecasts.
Conclusion
Linking range advantage recognition to sector rotation timing supplies mid-career traders with a structured method for navigating cyclical commodity futures, supported by positioning data and cycle research from regulatory and academic sources across multiple regions; the approach centers on consistent boundary definitions, regular data updates, and measured allocation changes that align with observed contract behavior rather than isolated predictions.